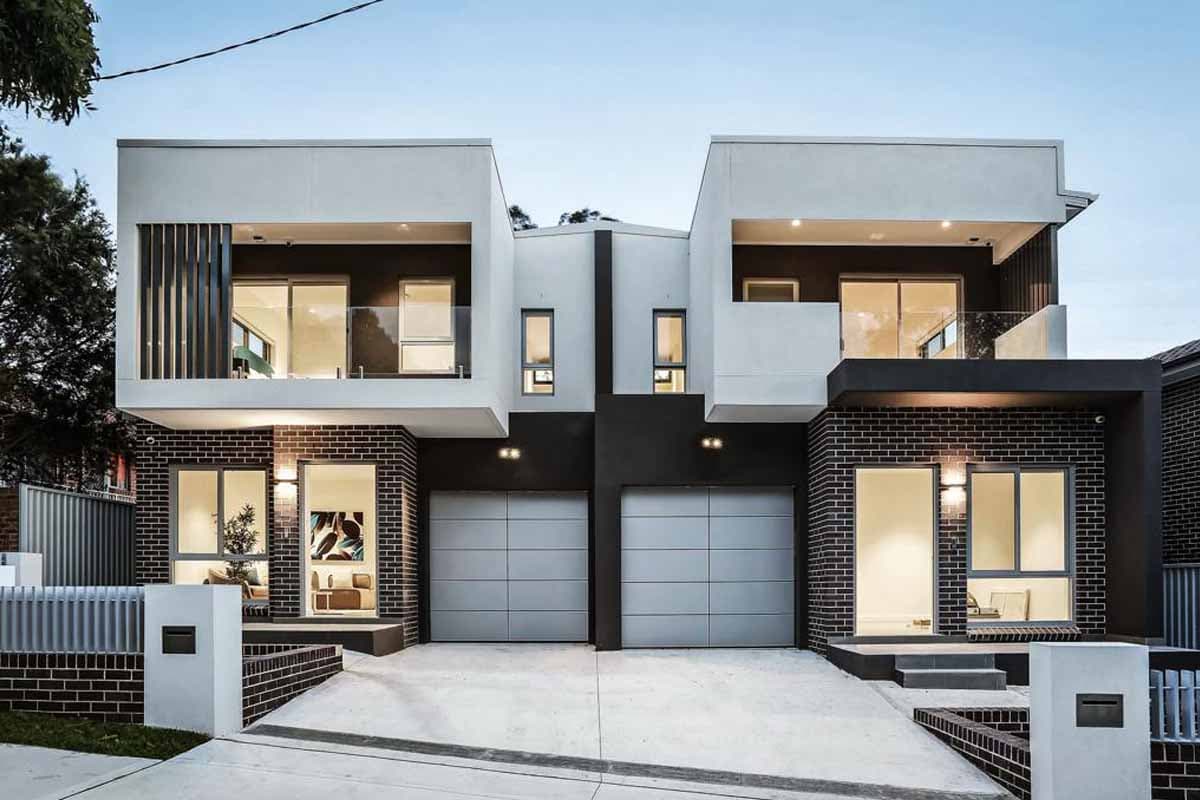
Tax on the sales that have settled, funded against the stock that has not.
- Indicative assessment within 2 business days, with settlement typically 2 to 6 weeks once valuations are in
- Loans from $250K to $10M
- Developers, builder-developers, and directors of project companies
- GST on new residential sales, income tax on project profit, and overdue BAS balances, secured against unsold stock, land, or the next site
- Full-doc (tax returns), low-doc or alt-doc (BAS, bank statements or an accountant's letter instead) and no-doc options across our 90+ lender panel
The project made money on paper. The tax is due before the last units sell. Some sales have settled, the construction loan has been reduced, and the profit and GST on those sales now have to be paid, while a large share of your capital sits in finished units waiting for buyers. ATO tax debt finance for property developers is a loan that pays the tax now, secured against completed stock, land you hold, or your next site, and repaid as the remaining sales settle. Joseph Farhat and his team work with developers at this exact point in a project, and they will give you a straight answer on what lenders will consider.
Who we can help access finance
- ✓Developers with completed townhouses or apartments still unsold, and a BAS balance from the sales that have already settled.
- ✓Project company directors whose income tax on project profit falls due while a large part of the profit is still held in stock.
- ✓Builder-developers whose margin scheme sales left a GST balance that the amounts withheld at settlement did not fully cover.
- ✓Developers whose ATO payment plan has defaulted, leaving the full overdue balance payable before the next sales settle.
- ✓Developers holding a new site with equity in it, who want to borrow against that land to clear the tax on the last project.
- ✓Developers moving off a construction facility at completion who want the tax debt dealt with in the same refinance.
How ATO Tax Debt Finance for Property Developers Works
On most sales of new residential premises, the buyer withholds GST and pays it straight to the ATO at settlement, and you receive the balance of the price. The amount withheld is generally 1/11 of the contract price, or 7% of the contract price where the margin scheme applies. That money is credited to your GST property credits account, then moves to your activity statement account when you lodge the relevant BAS, which can take up to 2 business days. Under the margin scheme, GST is broadly 1/11 of the margin (the sale price less what you paid for the property) rather than of the full price. It must be agreed in writing before settlement, and the buyer cannot claim a GST credit. Whether a balance is still owing once the withheld amounts are credited, and how much, is worked out by your accountant on the BAS.
Income tax is separate. Profit on the sales that have settled can be taxed while the remaining stock is still unsold, so the cash to pay it is tied up in the units you have not sold. Directors can also be personally liable for unpaid company GST through a director penalty notice, which is one more reason to deal with a GST balance early.
The finance itself is a property-secured loan. A lender advances funds against unsold stock, land, or another site, the ATO is paid, and the loan is repaid from the remaining sales or a later refinance. Lenders size it on a valuation of the security, so settlement takes longer than an unsecured loan. Joseph Farhat and his team review the stock schedule, valuations, sales evidence, and ATO balance, match the file to suitable lenders from a panel of 90+ bank, non-bank, and specialist lenders, and manage it through to settlement. We are a finance broker, not an accountant or tax adviser, and we describe GST mechanics only. Your accountant works out what is owed. If the project company may not be able to pay its debts as they fall due, speak with your accountant or a registered insolvency practitioner before borrowing.
What Lenders Assess for ATO Tax Debt Finance for Property Developers
Stock and security value
independent valuations of the unsold units, land, or next site set the loan size against the lender's maximum loan-to-value ratio (LVR), the loan as a share of the property's value.
Sales evidence
settled sales, contracts on hand, and recent comparable sales show how quickly the remaining stock is likely to sell and at what price.
Exit
a clear plan to repay the loan from settlements, a residual stock loan, or a refinance, with a realistic timeframe.
ATO position
an up to date ATO statement, BAS lodged for the periods with sales, and the figure from your accountant for any GST or income tax still owing.
Existing debt on the project
what is left on the construction facility or any residual stock loan, and whether that lender will agree to a second facility.
Track record
completed projects, sell-down history, and how this project ran against its feasibility.
The ATO Tax Debt Finance for Property Developers Process: What to Expect
- 1Make an Express Enquiry or call Joseph Farhat and his team. Tell them the tax owing, how many units are unsold, what other land you hold, and what finance is already on the project.
- 2Provide a stock schedule with asking prices, contracts on hand, an ATO account statement, tax figures from your accountant, and details of the existing facility.
- 3Joseph Farhat and his team give you an indicative assessment, usually within 2 business days, and match the file to lenders that fund against completed stock or land.
- 4The lender orders valuations and issues a formal approval with the rate, fees, LVR, term and exit terms. We go through the full cost with you before you sign.
- 5At settlement the ATO is paid as agreed. The loan is then reduced as remaining units settle, or refinanced at the end of the term.
Indicative Finance Options
| Lender Type | Indicative Rate | Max LVR | Typical Loan Range | Loan Term | Key Consideration |
|---|
| Bank | From ~7% p.a. | Up to 60% | $1M to $10M | 12 to 24 months | Strong sales evidence and full financials; a tax debt usually needs to be part of a wider refinance |
| Non-Bank Lenders | From ~8.5% p.a. | Up to 70% | $250K to $10M | 6 to 24 months | Residual stock or land security; alt-doc options; interest can often be capitalised |
| Private Finance | From ~1% per month | Up to 75% | $500K to $10M | 3 to 18 months | Available for unique scenarios |
Indicative figures only. Actual rates and terms depend on your project, financial position, property location, and lender assessment at the time of application. Rates are subject to change.
Why borrowers choose Settled With Joe for ATO tax debt finance for property developers
We represent you, not the lender
Joseph Farhat and his team act for you from the first call through to settlement.
Lenders who fund completed stock
appetite for unsold units varies sharply by location, product type, and number of units left, and we know which lenders on the panel take which.
Working with your existing lender
a second loan often needs the first lender to agree, and we plan the structure around that from the start.
The cost of the wrong lender
a short private term on stock that takes a year to sell can force a sale at the wrong price, so the term is matched to a realistic sell-down.
One conversation
one review of the project replaces a round of applications and repeat valuation fees.
90+ lenders on one panel
bank, non-bank, and specialist lenders, so a project with strong sales evidence can go to a bank at a sharper rate, and there are still options when it is more complex.
Private finance for unique scenarios
where bank and non-bank lenders are not the right fit, we can introduce you to private finance options.
Usually no direct cost to you
as a broker we are typically paid by the lender when the loan settles.
An honest answer early
if the BAS is due or the ATO has set a date, tell us early and we will tell you what is realistically achievable in that time.
Frequently asked questions
What is ATO tax debt finance for property developers?
It is a loan used by a developer or project company to pay GST, income tax or an overdue BAS balance owed on a project, secured against completed units, land, or another site. The lender pays the ATO, in full or to an agreed amount, and the loan is repaid from the remaining sales or a later refinance. It does not change the tax owed, only who it is owed to and when.
Can unsold units secure the loan?
Yes, completed and titled units are the most common security for this type of loan. Lenders value each unit and lend a percentage of the total, usually lower than for a single investment property because several units are being sold at once. Where a construction loan or residual stock loan is still in place, the new lender either takes a second mortgage with consent from the first lender or refinances the existing debt and the tax debt together. Joseph Farhat and his team will tell you which structure lenders are likely to accept for your project.
How does GST withheld at settlement affect what I owe?
On most new residential sales, the buyer pays GST directly to the ATO at settlement, generally 1/11 of the contract price, or 7% where the margin scheme applies. Those amounts are credited to your GST property credits account and move to your activity statement account when you lodge the relevant BAS. The GST you actually owe on each sale is worked out on your BAS, so a balance may remain once the credits are applied, or the credits may cover it. Your accountant calculates the figure. We arrange finance for whatever amount is confirmed as owing.
Can this sit alongside a residual stock loan?
Often, yes. If your residual stock loan has room within the LVR limit of that lender, the simplest path can be a single refinance that covers both the stock debt and the tax. If it does not, a second lender may fund against other land or property you hold, or take a second mortgage over the stock with consent from the first lender. Joseph Farhat and his team will check what your current facility allows before approaching anyone.
Can the loan be secured against my next site?
In many cases. Land you already own, with equity in it, can secure a loan that pays the tax on the last project, leaving the unsold units free to sell on their own timeline. Lenders look at the land value, any debt already on it, and how the loan will be repaid, whether from unit sales or the funding for the next project. Joseph Farhat and his team will tell you whether lenders on the panel are likely to accept the site as security.
Can I get ATO tax debt finance for property developers with low-doc or no-doc?
Yes, for many scenarios. Because the loan is secured against property, several non-bank lenders focus on the valuation, the sales evidence and the exit rather than full company financials. Lenders will still want BAS lodged for the periods with settled sales and the figure from your accountant for the tax owing, so the debt is known before funds are paid. No-doc options are available at lower LVRs. Joseph Farhat and his team will tell you what each lender needs for your project.
Do you work with borrowers with bad credit?
Yes, we do. A default, a past judgment, or a director with a listing on their personal file does not rule you out, and we will not make the conversation awkward. A long build or a slow sell-down can leave marks on a credit file that say little about the project itself. Several lenders on our panel give more weight to the value of the stock, the sales evidence and the exit than to the credit file, and price for the risk rather than decline it. Telling us early lets us approach the right lender first instead of adding enquiries to your file. Joseph Farhat and his team will tell you honestly what is achievable before you apply anywhere.
Why work with Settled With Joe to arrange your ATO tax debt finance for property developers?
Because one conversation replaces a round of applications and repeat valuations. Most of the people we help here are developers and project company directors working to a date: a BAS due on a run of settlements, income tax on project profit, a payment plan that has defaulted, or a construction loan reaching its end with stock still unsold. We see these situations often, and you will not be judged for being in one. What lenders care about is the value of the stock or land, the evidence that it will sell, and a clear exit. Our panel covers 90+ bank, non-bank, and specialist lenders, so a project with strong sales evidence can go to a bank at a sharper rate, and there are still options when it is more complex or the timing is tight. We are based in Sydney and work with developers Australia-wide. Joseph Farhat and his team will tell you honestly and early whether we can help and what is realistic in your timeframe.
Do you give financial advice?
No. We do not guide you on your finances, nor give financial advice. We focus on outcomes and solutions of presenting your unique scenario to the right lender so you can access funding in a timely and compliant manner.
Do you help with ATO tax debt finance for property developers outside Sydney?
Yes. Settled With Joe is based in Sydney and arranges ATO tax debt finance for property developers Australia-wide, in metro and regional areas. We work with developers in Sydney, Melbourne, Brisbane, Perth, Adelaide, and Canberra, as well as regional areas including Newcastle, Wollongong, Geelong, Gold Coast, Sunshine Coast, and Toowoomba. Joseph Farhat and his team will identify which lenders on the panel suit your project and timeframe.