
Urgent? Funding available within 2 business days across 90+ lenders. Call 0401 222 353
Settled With Joe
0401 222 353

Urgent Development Loan Refinance

Move a part-built project to a new lender and fund the work through to completion.

  • Indicative assessment within 2 business days.
  • Loans from $500K to $20M.
Call 0401 222 353
★★★★★5.0 from Google reviews
Development Loan Refinance
Indicative assessment within 2 business daysAcross 90+ lenders

Express Enquiry

Takes 60 seconds
Step 1 of 5

How can we help you?

Select the option that best describes what you need

Enquiring won’t affect your credit file. All details are secure, encrypted, and confidential.

★★★★★Joseph Alam
He came from a place of understanding
Getting a loan was difficult for me but not only did Joe get the loan done, he came from a place of understanding. Highly recommend and when I need to refinance at any stage I know who to see.
★★★★★Will M
Great experience from start to finish
Great experience from start to finish. Joe was professional, responsive and transparent throughout the entire process. He explained everything clearly and made it easy to move forward with confidence. Highly recommend for anyone looking for reliable and trustworthy financial services.
★★★★★John Safi
Easy the whole step of the way
Dealing with Joe was really easy the whole step of the way. He made it so easy to consolidate all my debts and get the best deals for me.
★★★★★Jack Roberts
Always gets you a great deal
Great mortgage broker. I have worked with Joe across multiple loans and never had any issues — efficient, professional and always gets you a great deal!
★★★★★Emilio Ayoub
Smooth and stress-free
Joe was awesome to deal with. Super knowledgeable, easy to talk to, and made the whole process smooth and stress-free. He explained everything clearly and worked hard to get the best outcome for us. Highly recommend Settled with Joe if you're looking for reliability, transparency and quality.
★★★★★Nick Jr Constantin
Clear and stress-free
Great experience working with Joseph during my home loan application. He was knowledgeable, responsive, and made the whole process clear and stress-free. I really appreciated his support and would happily recommend him to anyone needing help with property matters.
★★★★★Philip Albert
Actually makes the whole process easy
Highly recommend Settled with Joe if you're looking for a mortgage broker who actually makes the whole process easy. Joe was professional, knowledgeable, and always available to answer questions. He handled everything smoothly from start to finish and helped secure a great outcome without the usual stress that comes with finance.

An indicative answer on your part-built project, usually within 2 business days.

  • An indicative assessment usually within 2 business days of the core documents, so you know where you stand before the facility expires
  • Refinances from $500K to $20M, covering the payout plus the cost to complete
  • Developers and builders mid-build or near completion
  • Townhouses, apartments, duplexes, mixed-use and subdivision projects, most easily placed once past slab
  • Lenders accepting full-doc (tax returns), low-doc or alt-doc (BAS, bank statements or an accountant's letter instead) or no-doc, depending on the project

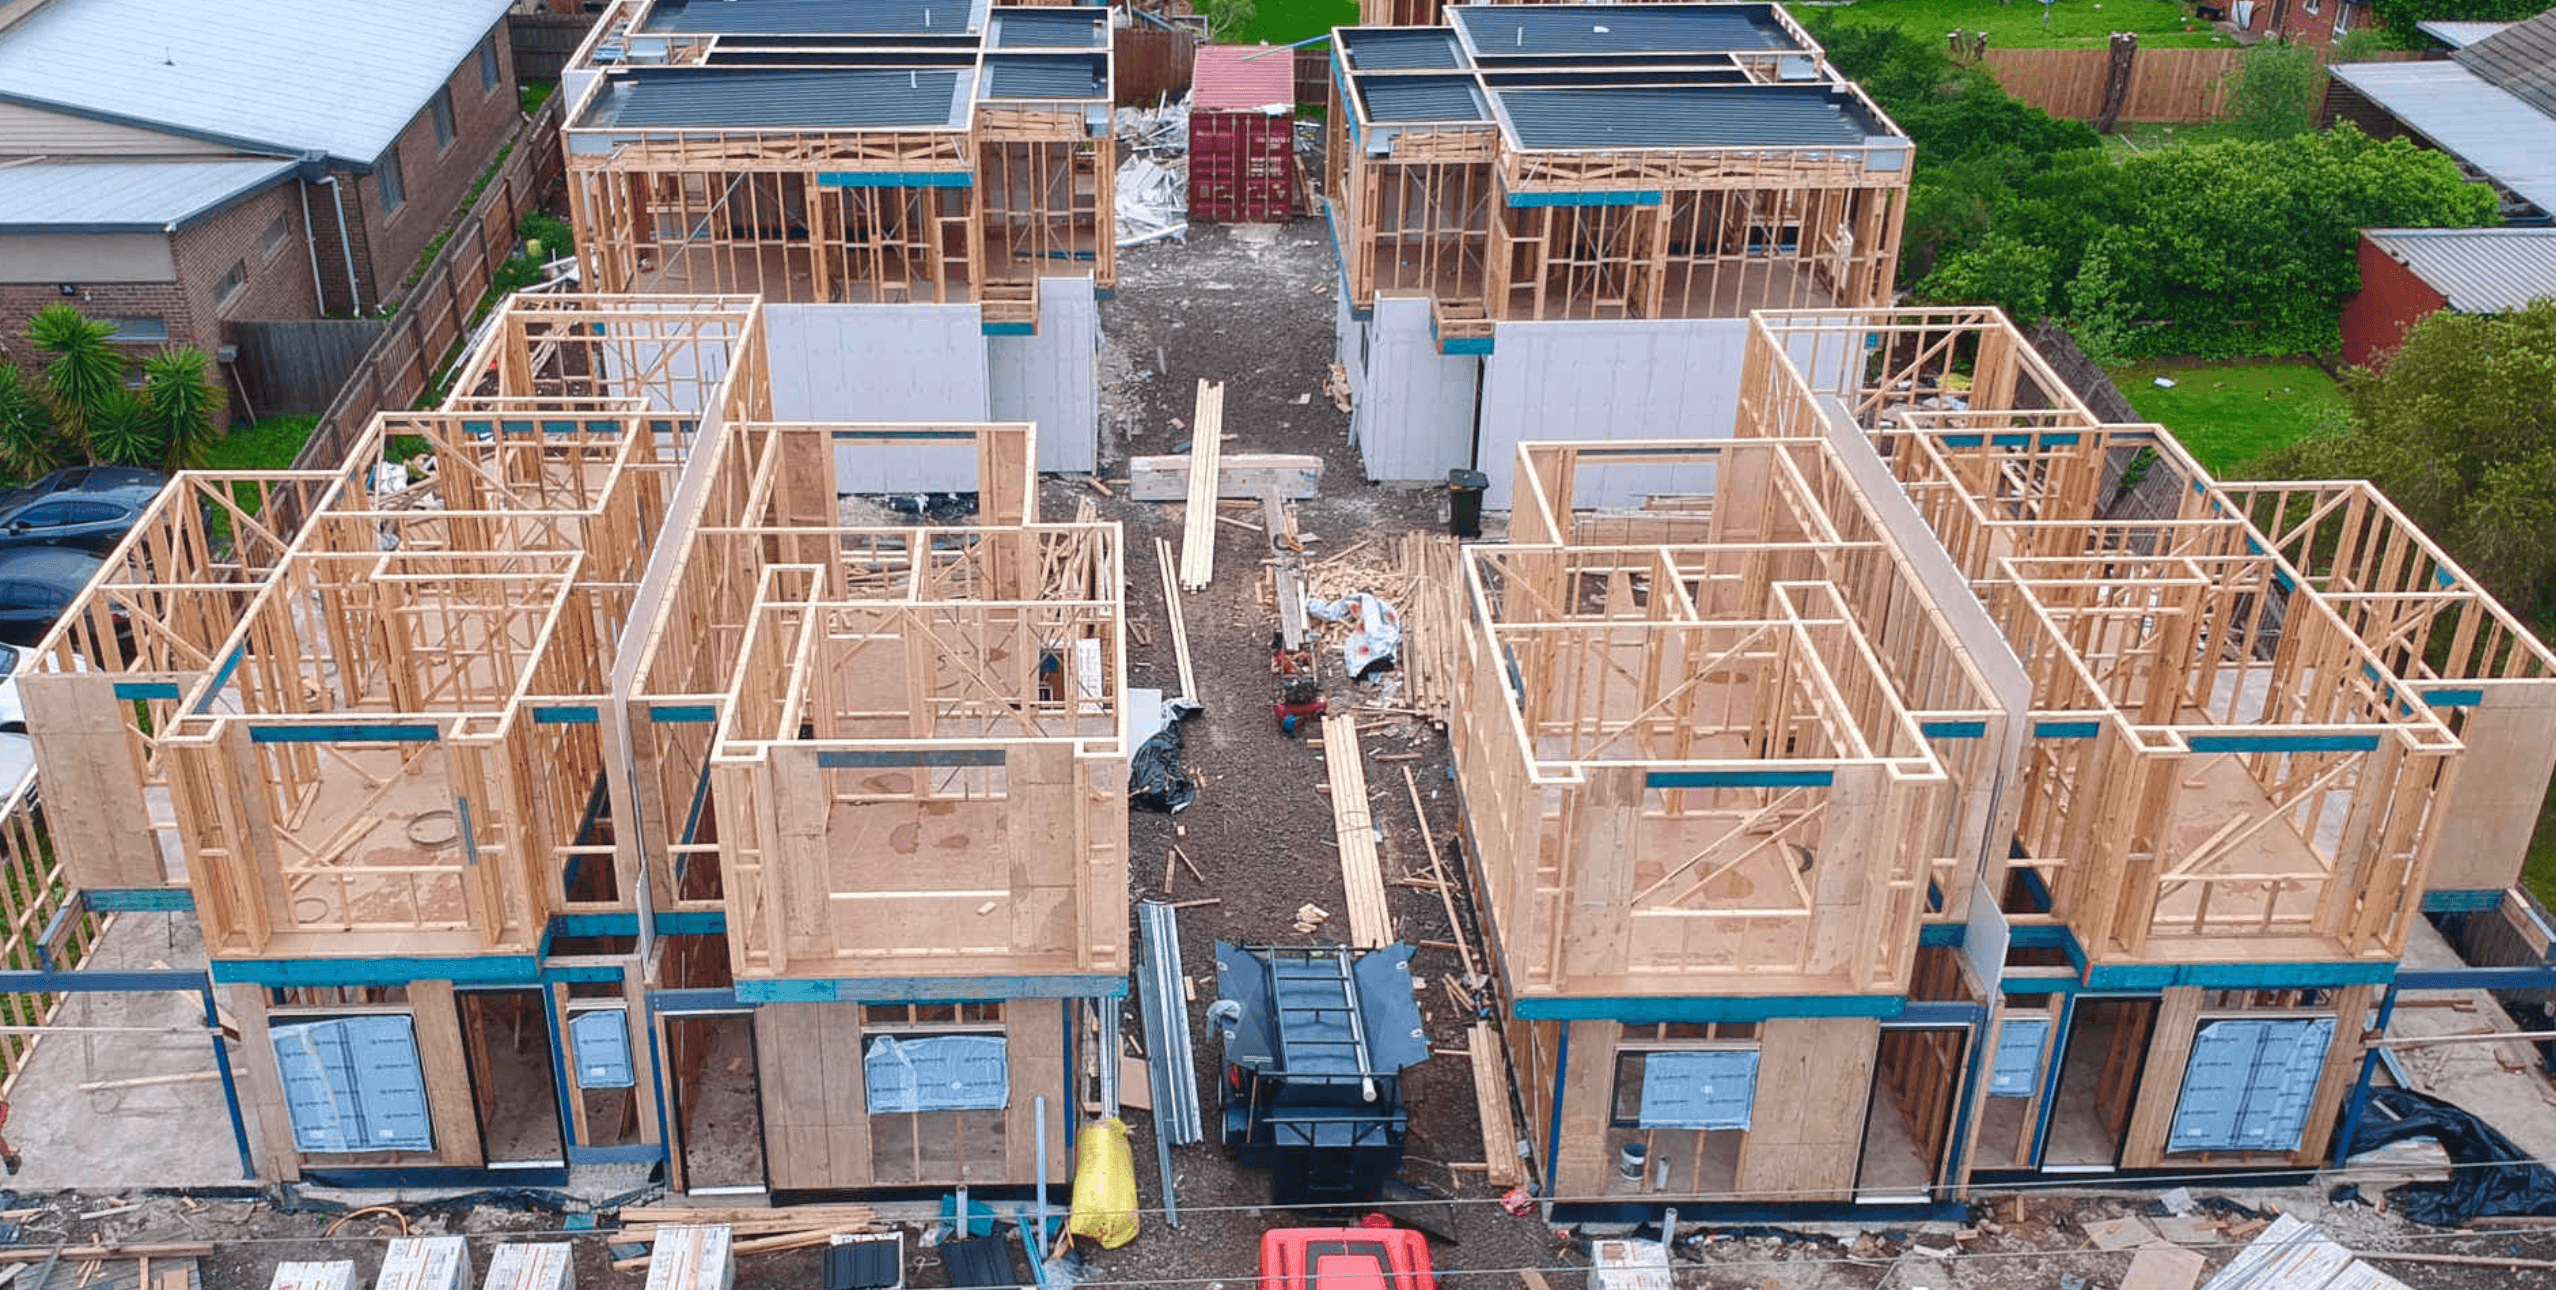
Half-built, and the facility ends before the build does. It happens on well-run projects. A wet winter, a trade shortage or a delayed approval can push completion past the maturity date. In other cases the lender offers an extension at a higher rate, or with new conditions, or has decided to reduce its development lending. None of that has to stop the build. A development loan refinance moves the project to a new lender, pays out the existing facility and funds the remaining work through to completion. Joseph Farhat and his team can help you find a lender with appetite for a part-built project, and give you an indicative answer while there is still time on the current facility.

Who we can help access finance

  • Developers with a maturity date coming up while the build still has several stages to go.
  • Developers who have been offered an extension at a higher rate or with new conditions and want to compare it with a refinance.
  • Builders developing their own project whose program moved after weather, a trade shortage or a council approval delay.
  • Developers whose lender has reduced its development lending and will not extend past the current date.
  • Developers near practical completion who need a short facility to finish the last stages and then move to a residual stock loan.
  • Developers with presales in place who need a new lender to recognise those contracts.
  • Self-employed developers with complex income whose project numbers are strong.

How Development Loan Refinance Works

Refinancing a partly built project is a different exercise from funding a new one. The new lender has to take on a site where some of the money has already been spent and some of the work is still to come. It needs three answers. What the project is worth today, as it stands. What it will be worth on completion. What it will cost to finish. The first two come from a valuation done on both bases. The third comes from a quantity surveyor (QS), who inspects the site, reviews the builder contract and the claims paid so far, and reports the cost to complete.

The new facility is sized to cover the payout of the existing loan, the cost to complete, capitalised interest for the rest of the build, and a contingency. The lender tests that total against the as-is and on-completion values, as a loan-to-value ratio (LVR), the loan as a share of the property's value. Where it falls short, the gap needs to be met by your own funds or by second-ranking finance such as mezzanine finance (a second loan that ranks behind the main lender). At settlement the incoming lender repays the existing facility and takes first mortgage over the site. From there, the remaining funds are released in progress draws against QS sign-off, in the same way the build was funded before.

Joseph Farhat and his team review the cost to complete, the valuations and the presale position, then take the project to the lenders among our 90+ bank, non-bank and specialist panel that fund part-built sites. Settled With Joe arranges the finance only. Presale contracts, sunset dates and the builder contract raise legal questions, so your solicitor is the right person to involve early.

What Lenders Assess for Development Loan Refinance

Cost to complete
the QS report on the work left to do, checked against the builder contract, variations and claims already paid.
As-is and on-completion values
a valuation on both bases, which sets how far the new facility can go now and at the end.
Payout figure
what the current lender needs to release its mortgage, with interest, fees and any extension costs included.
Builder position
the builder licence, how the project is tracking against the program, and whether the builder will sign a side deed (an agreement between the builder and the new lender).
Presales
the contracts in place, deposits held, buyer details and sunset dates, and whether they still support the sell-down.
Approvals and insurances
the development approval (DA), the construction certificate, contract works insurance, and any home building compensation cover the build requires.
Exit
sale of the completed stock, a residual stock loan for unsold units, or a refinance to a long-term loan if the project is being held.

The Development Loan Refinance Process: What to Expect

  1. Tell Joseph Farhat and his team where the build is up to, when the facility ends, what extension has been offered and what the payout looks like. You will hear honestly whether a refinance looks workable in the time available.
  2. In the first week, a new lender asks for the current loan statement and facility agreement, the builder contract and variations, the progress claims paid, the latest QS report, the DA and construction certificate, the presale schedule, insurance details, and your financials or bank statements.
  3. Once the core documents are in, we place the project with lenders that fund part-built sites, and you usually have an indicative assessment within 2 business days.
  4. The lender orders its own valuation and QS report, then issues an approval covering the facility limit, rate, drawdown schedule and conditions. We read through every condition with you first.
  5. Settlement day: the old facility is repaid and the new one takes over. Construction carries on, draws are released against QS sign-off, and at completion the loan is repaid from sales, a residual stock loan or a long-term refinance.

Indicative Finance Options

Lender TypeIndicative RateMax LVRTypical Loan RangeLoan TermKey Consideration
BankNot typically offered for refinancing a part-built project. May be considered near completion with strong presales.
Non-Bank LendersFrom ~9% p.a.Up to 65% of on-completion value$500K to $20M6 to 24 monthsQS cost to complete and valuations as-is and on completion required
Private FinanceFrom ~1% per monthUp to 70% of on-completion value$500K to $20M3 to 18 monthsAvailable for unique scenarios

Indicative figures only. Actual rates and terms depend on your project, financial position, property location, and lender assessment at the time of application. Rates are subject to change.


Why borrowers choose Settled With Joe for development loan refinance

We represent you, not the lender
Joseph Farhat and his team are on your side until practical completion.
We plan the switch around your maturity date
the QS report, the valuation and settlement are booked to land before the current facility ends.
We can compare an extension with a refinance
if your current lender offers an extension, we can set its cost beside the refinance options so you can decide with both in front of you.
We know which lenders take on part-built sites
many lenders only fund from the start of a project, and approaching the right few first saves weeks.
The handover is coordinated
payout figures, the builder side deed and insurances all need to line up on one settlement day, and we keep each party moving.
A panel of 90+ lenders
bank, non-bank and specialist, so a near-complete project with strong presales may still suit a bank, and a build at frame stage has other routes.
Private finance for unique scenarios
for a project outside bank and non-bank policy, we can introduce you to private finance options.
Usually no direct cost to you
brokers are typically paid by the lender when the loan settles.
An honest answer early
with a facility ending before the build does, a call this week tells you what can realistically be done in the time left.

Frequently asked questions

What is a development loan refinance?
A development loan refinance replaces an existing construction or development facility with a new one before the project is finished. The new lender pays out the current loan, then funds the remaining build through progress draws. It is usually used when the facility will mature before completion, when extension terms have changed, or when the current lender is reducing its development lending.
Can a project be refinanced mid-construction?
Yes. Several lenders on our panel will refinance a project part way through the build, provided the cost to complete is clear and the numbers still work. They look closely at how much work is left, how the builder is tracking and whether the funds will reach completion. Projects past slab with a clear QS report are generally easier to place than very early-stage sites. Lender appetite changes, so Joseph Farhat and his team will check who is lending on part-built projects now.
Who pays the QS and valuation?
In most cases, the borrower. The incoming lender usually orders the valuation and the QS report from its own panel, because it needs reports addressed to it. Depending on the lender, these costs are paid upfront or out of the first advance. Reports done for your current lender are useful background, but a new lender often cannot rely on them. Joseph Farhat and his team will tell you the expected report costs before you commit.
What happens to existing presales?
The presale contracts are between you and your buyers, so they stay in place when the loan moves. The new lender reviews them as part of its assessment: the buyer, the deposit, whether the contract is unconditional and the sunset date. A sunset date that falls before the revised completion date needs attention, and that is a question for your solicitor. Contracts that still stand can support the new facility, just as they supported the old one.
How long does a development loan refinance take?
It varies with the project and the lender. The indicative assessment usually comes within 2 business days of the core documents. The valuation and QS report then take time to book and complete, and the lenders and solicitors on both sides need to coordinate settlement. Starting several weeks before the maturity date gives the most options. If the date is close, tell us at the first call.
What if the new facility will not cover the payout and the cost to complete?
The new lender will not settle until the gap is covered. That can be done with your own cash, equity in another property, or second-ranking finance such as mezzanine finance. A lender with a higher limit, or a scope change agreed with the builder, can also close it. Where the company may be unable to meet its debts when they are due, the first call is to your accountant or a registered insolvency practitioner. We can look at finance once they have given you their view.
Can I refinance a development loan with low-doc or no-doc?
In many cases. The QS report, the two valuations and the exit carry most of the weight here, and some non-bank lenders on the panel will work from BAS, bank statements or an accountant letter. No-doc refinances are possible for strong projects. Expect a lower loan limit and a higher rate with less paperwork, and the keenest pricing where full financials are available.
Do you work with borrowers with bad credit?
Yes, we do. A default, arrears or a judgment on your file does not rule out a development refinance, and the conversation will not be uncomfortable. Many listings trace back to a tough stretch on an earlier project. They tell a lender very little about the work already in the ground or what it costs to finish. Some lenders on our panel give the QS report, the valuations and the exit more weight than the credit history, and set a rate for the risk instead of saying no. Raising it at the first call lets us go to a suitable lender straight away and keeps unnecessary enquiries off your file. Joseph Farhat and his team will give you a straight answer on what is possible before any application goes in.
Why work with Settled With Joe to arrange your development loan refinance?
You speak to one team, and that team approaches the lenders, rather than you applying to several yourself. The developers, builders and company directors who call us about a refinance are usually facing a fixed date: a facility maturity, an extension offer that must be accepted by a deadline, or a lender stepping back from development. These situations are familiar to us, and there is no judgement in the conversation. Lenders focus on the cost to complete, the as-is and on-completion values, and a clear exit. With 90+ bank, non-bank and specialist lenders on the panel, a near-complete project with full financials may suit a bank at a keener rate, and a build at an earlier stage, or on a short deadline, has other routes. We are based in Sydney and help developers in every state. Joseph Farhat and his team will tell you early and honestly whether a refinance can settle before your facility ends.
Do you give financial advice?
No. We do not guide you on your finances, nor give financial advice. We focus on outcomes and solutions of presenting your unique scenario to the right lender so you can access funding in a timely and compliant manner.
Do you help with development loan refinance outside Sydney?
Yes. Settled With Joe is based in Sydney and arranges development loan refinance Australia-wide, covering both metro and regional areas. We work with clients in Sydney, Melbourne, Brisbane, Perth, Adelaide, and Canberra, as well as regional areas including Newcastle, Wollongong, Geelong, Gold Coast, Sunshine Coast, and Toowoomba. Appetite for part-built projects varies by location, and QS and valuer availability can affect timing in regional areas. Joseph Farhat and his team will identify which lenders on the panel suit your site and your remaining build time.

Client success

Recent settlements

View all case studies →

What clients say

Access to over 90+ bank, non-bank, and private lenders

MacquarieNABWestpacANZSt.GeorgeBankwestSuncorpAMP BankINGBOQBendigo BankPepper MoneyResimacBluestoneFirstmacLibertyLa Trobe FinancialJudo BankQualitasThinktank
Related to Development Loan Refinance 4
Business finance 42
ATO and tax debt 15
Construction and development 7
Personal finance 31
By industry 6

We’re here to help

Tell us the deadline and the scenario. You’ll get an honest answer early. Enquiring won’t affect your credit file. No obligation.

0401 222 353












