
Construction finance structured around your build program and your settlement date.
- Indicative assessment within 2 business days, then staged drawdowns across the build
- Loans from $200K to $20M
- Builders, developers, owner-builders, and self-employed ABN holders
- Duplexes, townhouses, boarding houses, knockdown rebuilds, and multi-dwelling sites
- Full-doc (tax returns), low-doc or alt-doc (BAS, bank statements or an accountant's letter instead), and no-doc options, including lenders who do not require units to be sold before the build starts
Construction finance funds a build in stages rather than as a single advance. The lender assesses the project on what it will be worth when it is finished, releases funds progressively as the work is completed, and charges interest only on what has been drawn. It suits investors and builders building to sell or hold: a knockdown rebuild on an investment site, a duplex, townhouses, or a small multi-dwelling site. What varies most between lenders is documentation, how they treat owner-builders, and how quickly they release each progress payment. Joseph Farhat and his team will tell you honestly and quickly what is achievable for your situation.
Who we can help access finance
- Investors and builders building to sell or hold, including knockdown rebuilds on investment sites.
- Investors building a duplex or a secondary dwelling to hold for rental income.
- Investors buying a site who need the land settled and the build funded together.
- Self-employed borrowers and ABN holders with strong equity whose income does not present neatly in two years of returns.
- Borrowers who need land settled quickly while the construction facility is still being documented.
- Owner-builders, where the lender list narrows considerably and the loan-to-value ratio (LVR), the loan as a share of the property's value, is usually lower.
- Builders and investors whose existing facility has stalled at a progress draw and needs refinancing to complete.
- Anyone building something less conventional: kit homes, modular, container, or an unusual site.
Building a home you will live in? That is consumer lending, and it is covered on our home loans page.
How Construction Finance Works
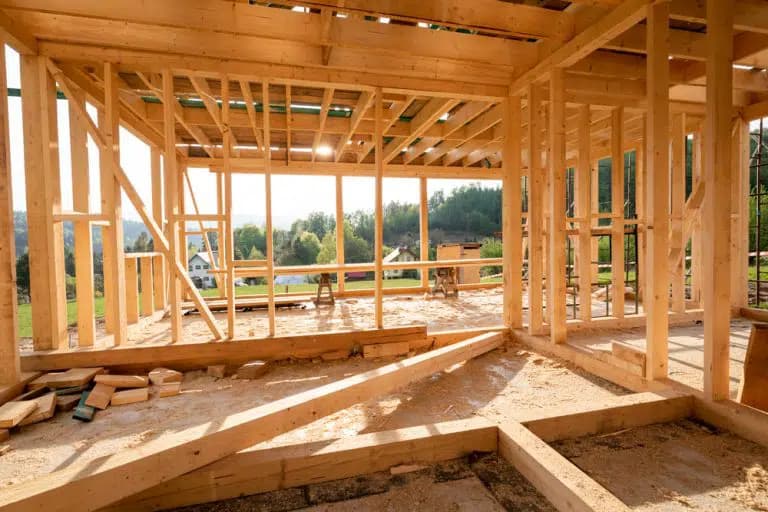
The lender approves a total facility based on the land value plus the cost of the build, tested against the on-completion valuation. Funds are then released in progress payments tied to construction stages: slab, frame, lock-up, fixing, and practical completion. Before each release the lender usually requires an inspection or a valuer sign-off. You pay interest only on the balance drawn, so holding costs are lowest at the start and rise as the build progresses. At practical completion the facility either converts to a standard loan or is refinanced. Joseph Farhat and his team review the contract, the site, and your position, match the scenario to the right lender from the 90+ panel, and manage the application through to practical completion.
What Lenders Assess for Construction Finance
On-completion valuation
The building contract
Builder credentials
Contingency
Documentation available
Serviceability during the build
Owner-builder status
The site itself
The Construction Finance Process: What to Expect
- Talk to Joseph Farhat and his team about the site, the build, and what documentation you can produce. You will get an honest read on what is achievable before you sign a building contract.
- Provide the basics: the building contract and plans, council approval, the land contract or title, your builder’s licence and insurance details, and your financials or bank statements.
- We match your scenario to the lenders on the panel most likely to fund the build at a sensible LVR and rate. Contract type and owner-builder status change the lender list sharply, so this step matters.
- The lender orders an on-completion valuation and issues an approval setting out the facility limit, rate, drawdown schedule, and conditions. We go through it with you before you sign anything.
- Land settles if required, construction begins, and progress payments are released stage by stage. We stay involved through the draws, which is where most construction facilities actually run into trouble.
Indicative Finance Options
| Lender Type | Indicative Rate | Max LVR | Typical Loan Range | Loan Term | Key Consideration |
|---|---|---|---|---|---|
| Bank | From ~6.5% p.a. | Up to 80% on completion | $200K to $20M | 12 to 24 months | Fixed price contract and full income documentation usually required |
| Non-Bank Lenders | From ~8.5% p.a. | Up to 75% on completion | $200K to $20M | 6 to 24 months | Alt-doc and low-doc options, and faster assessment |
| Private Finance | From ~1% per month | Up to 70% on completion | $500K to $20M | 6 to 24 months | Available for unique scenarios |
Indicative figures only. Actual rates and terms depend on your project, financial position, property location, and lender assessment at the time of application. Rates are subject to change.